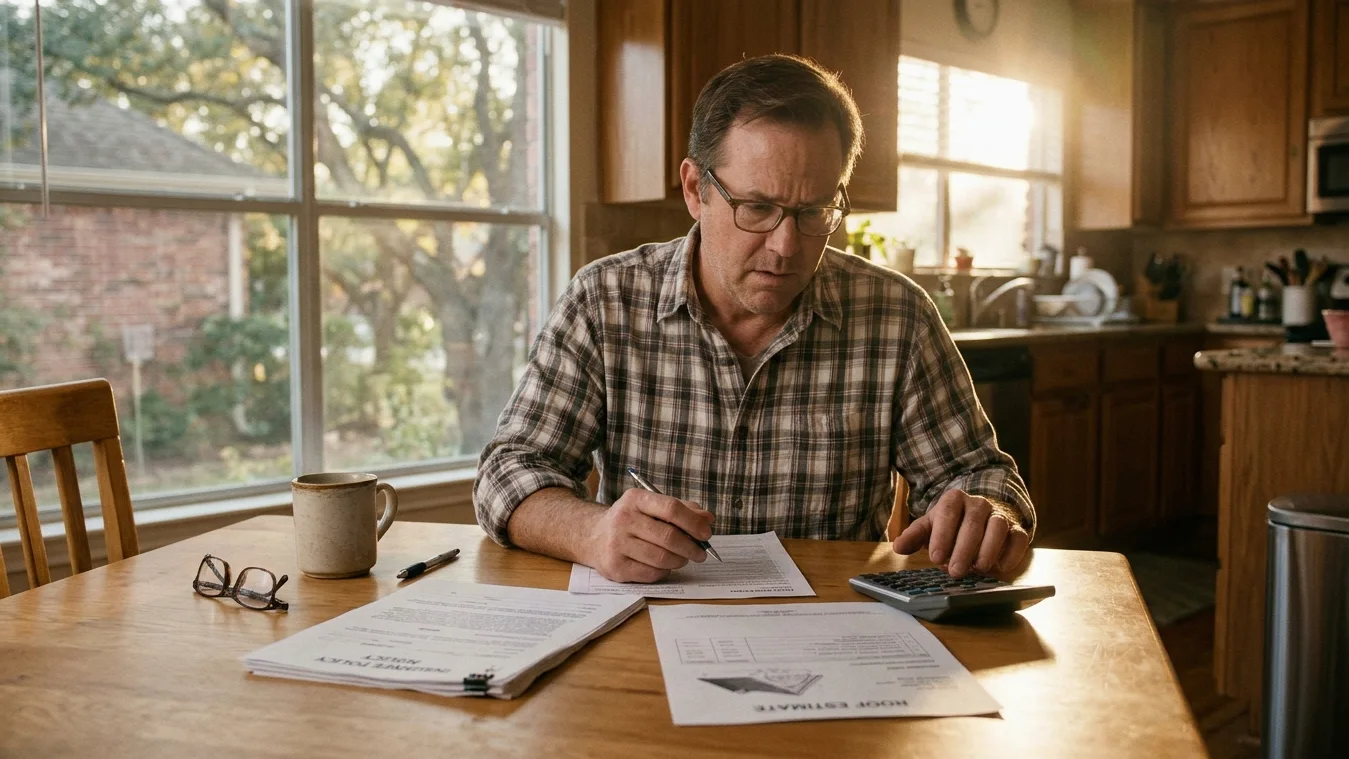
The deductible is a percentage of the house, not the damage
Many Texas homeowner policies use a percentage deductible for wind and hail, often 1% to 2% of dwelling coverage. That percentage is figured from the dwelling limit on your policy, sometimes called Coverage A, not from the size of the claim. This catches a lot of Dallas homeowners off guard because the number grows every year as the dwelling limit goes up at renewal.
Here's the simple version. If your dwelling limit is $400,000 and your wind and hail deductible is 2%, your deductible is $8,000. At 1% it would be $4,000. Most policies also carry a separate flat dollar deductible for everything else, like a kitchen fire or a burst pipe. Wind and hail claims use the percentage one, which is why a roof claim can feel very different from any claim you've made before.
A worked example
Say a May hailstorm damages your roof and the adjuster writes the replacement at $17,850. Here's how that plays out on a policy that pays full replacement cost. Notice that your share stays at $8,000 whether the claim is $9,300 or $32,600. On a $9,300 claim the insurer pays $1,300, and on a $32,600 claim covering the roof, gutters and fence it pays $24,600. That's why a percentage deductible stings most on mid-size claims, and why it helps to know your exact number before a storm.
- Dwelling limit on the declarations page: $400,000
- Wind and hail deductible: 2%, which equals $8,000
- Replacement cost of the roof work: $17,850
- Amount the insurer pays: $17,850 minus $8,000, or $9,850
- Amount you pay toward the roof: the $8,000 deductible
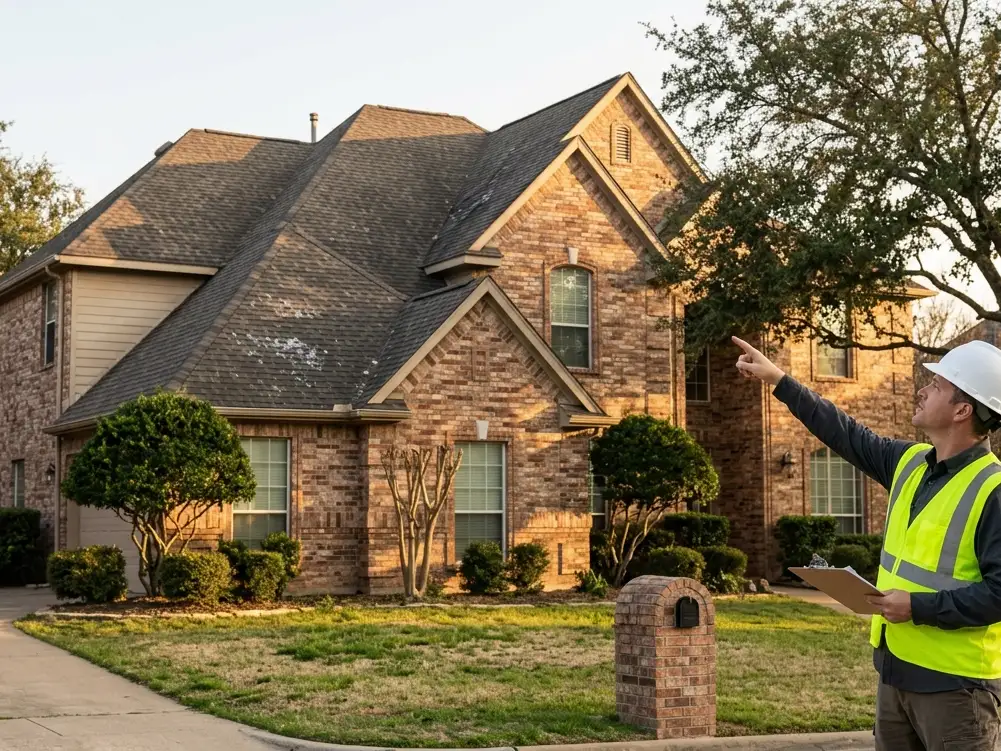
ACV versus RCV
Replacement cost value, or RCV, is what it costs to put a new roof on today. Actual cash value, or ACV, is that number minus depreciation for age and wear. Which one your policy uses for the roof makes a big difference, and some Texas policies pay the roof on an ACV basis or use an age-based schedule even when the rest of the house is covered at replacement cost.
Using the same example, suppose the adjuster figures $6,240 in depreciation on a twelve-year-old roof. The ACV is $17,850 minus $6,240, or $11,610. Subtract the $8,000 deductible and the payment is $3,610. On many RCV policies, the insurer pays the ACV amount first and releases the withheld depreciation, often called recoverable depreciation, after the work is finished and a final invoice is sent. On a true ACV policy, that depreciation is simply not paid. Small claims can also fall under the deductible entirely, so a $6,900 repair on an $8,000 deductible pays nothing.
Chapter 707: nobody can cover your deductible
Texas Insurance Code Chapter 707 makes it illegal for a contractor to waive, absorb or rebate a homeowner's deductible. That includes the creative versions you might hear at the door: an advertising payment for a yard sign, a discount that happens to equal the deductible, or a promise that the roof will cost you nothing. If the deal sounds like the deductible disappears, it's the kind of deal the law was written to stop.
Honest roofers write the contract at the real price, and the deductible is your share of it. We collect it the same way we collect any other part of the contract. If a company offers to make it go away, that's a reason to keep looking, because the same company is likely cutting corners somewhere you can't see, and it puts your claim at risk too.
SB 458 and the appraisal provision
Senate Bill 458 requires an appraisal provision in residential property policies issued or renewed after January 1, 2026. Appraisal is a way to settle a disagreement over the amount of a loss without going to court. In general, you and the insurer each choose an appraiser, the two appraisers pick an umpire, and an agreement between any two of them sets the amount.
Appraisal usually settles how much the loss is worth, not whether something is covered in the first place, and each side typically pays its own appraiser. The details depend on your policy wording, so read that section when your renewal arrives. If you think the adjuster missed damage, the first step is usually a reinspection with photos and a line-item estimate in hand.
Read your own declarations page
The declarations page is the summary sheet at the front of your policy, and it answers most of these questions in a few lines. Pull it up before storm season and look for these items. If you can't find it, your agent or the carrier's app can usually send a fresh copy in a few minutes.
- Your dwelling limit and the wind and hail deductible, as a percentage and in dollars
- The flat deductible for all other perils
- Whether the roof is paid at replacement cost, actual cash value or on an age-based schedule
- Any cosmetic damage exclusion, which matters most on metal roofs
- The deadline for reporting a loss
Where we fit in
We are not insurance advisors, and nothing here is a reading of your specific policy. Questions about coverage, deductibles and appraisal belong with your agent or carrier. What we do is the roof side: inspect it, photograph every slope, write a line-item estimate and meet the adjuster on site so the damage gets measured accurately.
We can also tell you what the damage looks like, what it costs to fix at Dallas market prices, and how that figure compares with the deductible you've told us about. Many homeowners find that useful before they call their carrier, because it puts the deductible next to a real repair number instead of a guess. If you want that documentation after a storm, call us at (214) 910-6728.
Questions homeowners ask
Why did my wind and hail deductible go up when I didn't change anything?
Because the percentage is tied to your dwelling limit, and many policies raise that limit at renewal to track rebuilding costs. A 2% deductible on a $360,000 limit is $7,200, while the same 2% on $400,000 is $8,000. Check the dollar figure on each new declarations page rather than assuming it stayed the same.
Can I switch to a lower wind and hail deductible?
Many insurers offer more than one deductible option, and a lower percentage usually comes with a higher premium. Some carriers limit changes once storm season starts or after a recent claim. Your agent can show you the price difference so you can weigh the yearly cost against what you'd pay out of pocket after a storm.
Is it worth filing a claim if the damage is close to my deductible?
Often it isn't, because the payment would be small or nothing and the claim still goes on your history. Get an honest estimate first. If the repair is well under the deductible, paying for it directly may make more sense. If it's close, ask your agent how a claim could affect your renewal before you file.