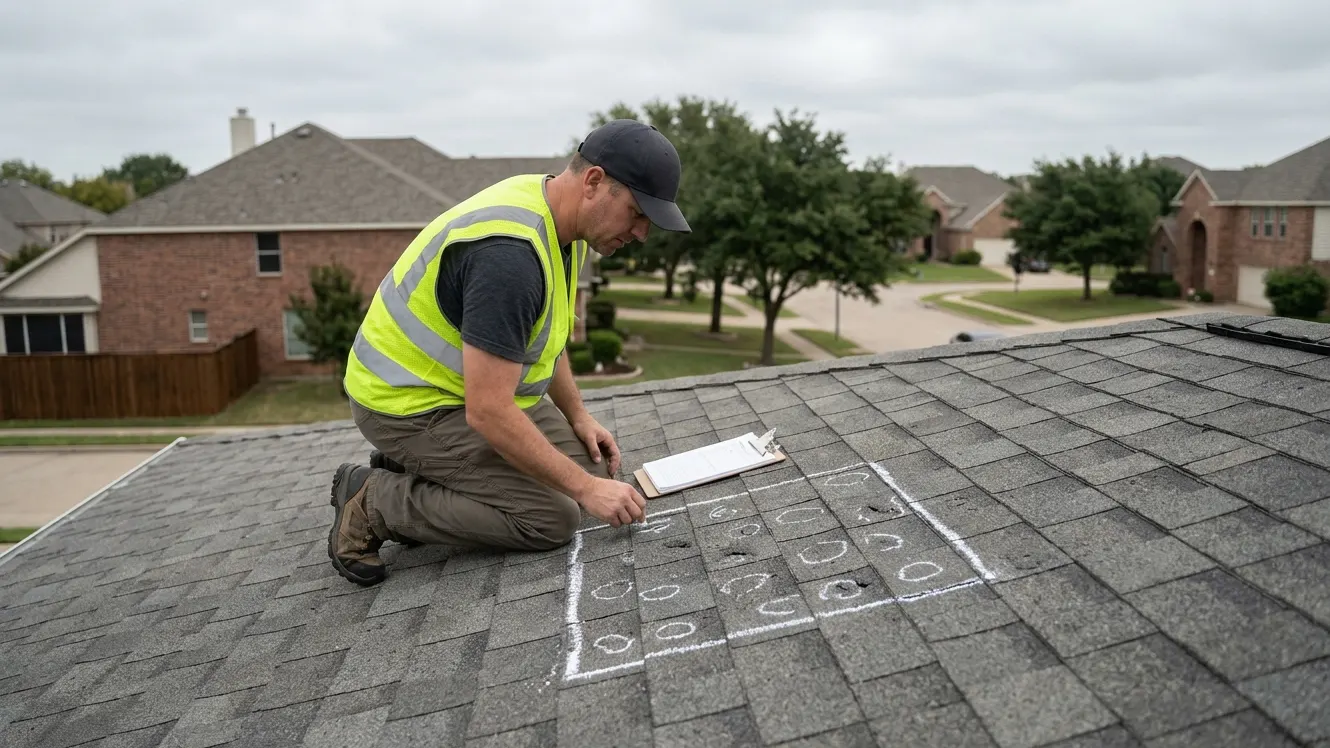
Storm damage claim help means we inspect your roof after hail or wind, document the damage, meet the adjuster to show it, then repair or replace the roof once your claim is approved. Dallas homeowners use it after spring storms. The inspection is free; you pay your deductible, and the remaining repair cost follows your insurer's approved scope.
Our role in a storm claim is simple and limited. We inspect your roof, document every sign of hail or wind damage with dated photos and measurements, and meet your insurance adjuster on the roof to point out what we found. Once the claim is decided, our crews do the repair or replacement. We do not act as a public adjuster, we do not negotiate your settlement, and we do not sign anything on your behalf. You stay in charge of your claim; we stay in charge of the roof.
That distinction matters in Texas. Only a public adjuster or an attorney can represent a homeowner in negotiating a claim, and a contractor who tries to do both is breaking the rules. What a roofer can do well is show the adjuster physical evidence: bruised shingles, dented vents, split ridge caps, collateral marks on gutters and fences. Clear evidence on the roof is what moves an adjuster's report, and that is the part we handle.
Signs you may have a roof claim
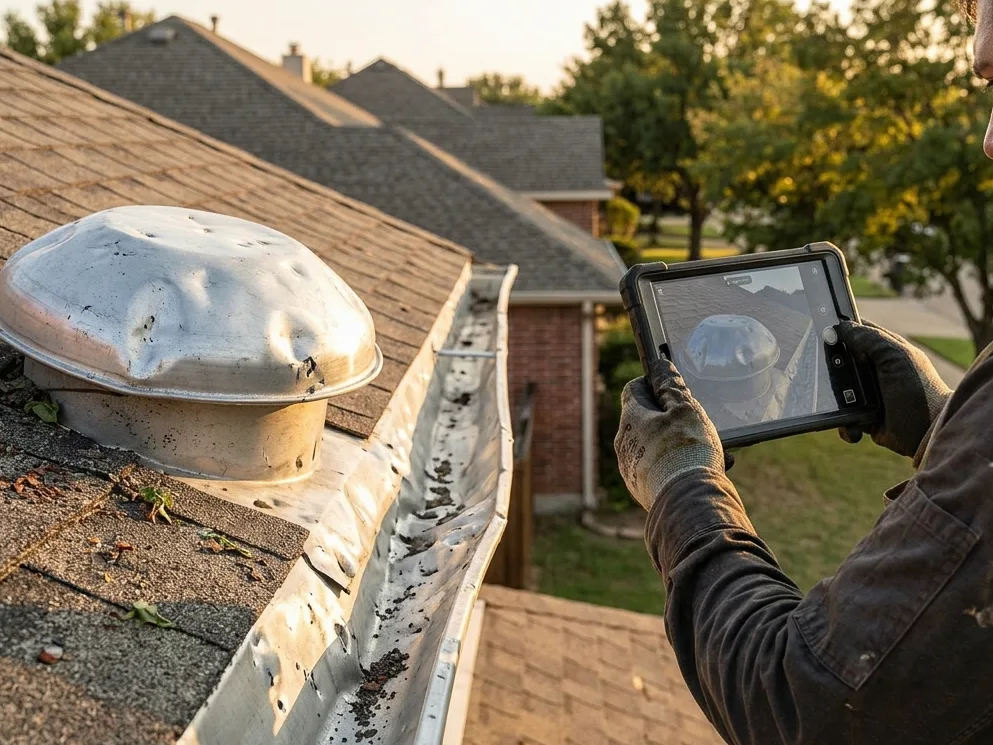
- Dents on soft metals: Hail marks on gutters, downspouts, vent caps and AC fins show how big the stones were.
- Granules in downspout splash: A sudden pile of shingle grit after a storm points to fresh hail hits.
- Neighbors getting roofs: When several houses on your street have adjusters out, your roof likely took the same hit.
- Lifted or creased tabs after wind: Shingles that bent back in gusts lose their seal and often tear later.
- Cracked skylight domes or tiles: Hard surfaces break under large hail and are easy to document.
- New leaks after a storm: Water inside a day or two after severe weather often traces to wind or hail damage.
How we help with a storm damage claim
- We inspect the full roof, mark test squares on each slope, and photograph hail hits, wind creases and soft-metal dents.
- We record storm date, hail size estimates from collateral damage, and slope-by-slope counts in a report you can send your insurer.
- You file the claim with your carrier directly, and we tell you what our inspection found so you can describe the damage accurately.
- We meet the adjuster on the roof, walk the test squares together, and show the physical evidence of each damaged area.
- If the adjuster's scope misses items like drip edge, vents or code-required parts, we document them so you can ask your insurer to review.
- Once the claim is settled, our crews do the repair or replacement, and you pay the deductible exactly as your policy states.
Insurance claims in hail alley: what Dallas homeowners should know
DFW sits in hail alley, and the peak season runs roughly March through June. Storms like the April 2016 hail events in Wylie, Plano, Garland and Murphy, or the October 2019 tornado through Preston Hollow and Walnut Hill, produced waves of claims and waves of storm chasers knocking on doors. Many Texas homeowner policies use a percentage wind and hail deductible, often 1% to 2% of dwelling coverage, so on a $450,000 home that deductible could be $4,500 to $9,000. Read your declarations page before a storm, not after.
Texas Insurance Code Chapter 707 makes it illegal for a contractor to waive, absorb or rebate a homeowner's insurance deductible, including through fake discounts, gift cards or advertising credits. We never do it, and you should be wary of anyone who offers. Most policies also require prompt notice of damage, so call your carrier soon after the storm and keep every photo, receipt, estimate and letter from the insurer together in one folder.
How claims usually end, and what happens next
Every claim lands in one of a few outcomes once the adjuster files a report. Knowing them ahead of time helps you plan, and helps you decide whether to ask your insurer for a review. Here is how each one usually plays out with us.
| Outcome | What it means | What happens next |
|---|---|---|
| Full replacement approved | Damage was enough to replace the roof | We schedule the reroof, pull the permit where required, and you pay your deductible. |
| Partial repair approved | Only certain slopes or parts were damaged | We repair the approved areas and tell you honestly if a mismatch issue remains. |
| Damage below deductible | Repair cost is less than your deductible | No payout, so we price the repair directly and you decide whether to proceed. |
| Claim denied | Adjuster found no covered storm damage | You may ask your carrier for a reinspection; we can share our photos with you. |
| Supplement needed | Hidden items found during tear-off | We document decking or flashing found under the old roof for your insurer to review. |
What storm damage insurance claims costs in Dallas
| Storm inspection and photo report | $0 |
| Adjuster meeting on your roof | $0 |
| Reinspection report for a claim review | $145 to $385 |
| Upgrade from standard to Class 4 shingles, per square | $95 to $185 |
| Emergency tarp before the adjuster visit | $385 to $1,240 |
The storm inspection and adjuster meeting cost you nothing. What you pay toward the roof depends on your policy: the deductible always comes out of your pocket, and some policies pay actual cash value first, then release depreciation after work is done. Items your insurer does not cover, such as upgrades you choose, are priced separately and in writing.
Before filing, run your numbers through our wind and hail deductible calculator.
How the job runs
Call
Book the visit. Tell us why you want the roof looked at: a storm, a sale, an insurance question or plain age. That decides how we document it.
Climb
Slope-by-slope inspection. We check shingles or panels, flashing, vents, gutters and the attic side, and mark storm hits so they show clearly in photos.
Report
Photos and findings. You get dated photos and plain findings: what is damaged, what is worn, what is fine and what can wait.
Plan
Repair, claim or wait. We tell you which of the three makes sense. If a claim fits, we can meet the adjuster on the roof and show what we found.
Follow up
Records you keep. Keep the report with your policy papers. It helps with the next storm, the next sale and the next renewal.
Storm Damage Insurance Claims questions
Can you negotiate with my insurance company for me?
No. In Texas, only a public adjuster or an attorney may represent you in negotiating a claim. We document damage and show it to the adjuster on the roof, and we can explain what we found to you. Decisions about your settlement, appeals and paperwork stay with you and your insurer.
Will you cover my deductible or give me a discount to offset it?
No. Texas Insurance Code Chapter 707 makes it illegal for a contractor to waive, pay or rebate a homeowner's deductible, and that includes hidden discounts or rebates. You pay the deductible your policy states. Anyone who offers to eat it is putting both of you at legal risk.
What is a percentage wind and hail deductible?
Many Texas policies set the wind and hail deductible as a percentage of dwelling coverage, often 1% to 2%, instead of a flat dollar amount. On a home with $380,000 in dwelling coverage, a 2% deductible is $7,600. Check your declarations page so you know the number before deciding whether a claim makes sense.
How long do I have to report storm damage?
Policies require prompt notice, and Texas law sets outer limits on filing. Waiting makes it harder to tie damage to a specific storm, especially when several storms hit in one season. Call your carrier soon after you notice damage, and let us inspect so you have dated photos to back up your report.